Rivel Banking Research
Why Do Customers Switch Banks?
About one-third of consumers are vulnerable to switching their primary banking relationship at any given time. Rivel's national research shows how life events, generation and channel influence when consumers change banks or open accounts elsewhere.
Research conducted April 2025 · Last reviewed August 2026 · Methodology
Behind the 33%
Switching risk is persistent, but the opportunity is not evenly distributed.
What converts that standing vulnerability into an actual switch is usually something specific: a fee increase, a service failure, an acquisition—or a life event that changes what a consumer needs from a bank.
Life events do the most work among younger consumers. The report notes that those under 26 typically hold less at their primary institution, so there is less to move, and more to gain from consolidating on rate, accessibility or simplicity. Some switch their primary bank outright during the transition—others open an account elsewhere and leave the rest where it is. The tables below separate the two.
Which moments, and for whom
Which life events are associated with switching banks?
Among consumers who experienced these events in the prior five years, Rivel found the following shares who switched banks during the event. Dashes indicate that the source report did not publish a percentage for that generation/event combination.
| Life event | Gen Z | Millennials | Gen X | Boomers |
|---|---|---|---|---|
| Began attending college | 22% | — | — | — |
| Joined workforce | 24% | 28% | — | — |
| Got married | — | 32% | — | — |
| Became a parent | 30% | 25% | — | — |
| Switched careers/jobs | 32% | 37% | 24% | — |
| Bought a home | — | 24% | 27% | — |
| Death/illness of a loved one | — | 13% | 8% | 4% |
| Retired | — | — | 14% | 9% |
Highest reported switching rate: 37% of Millennials who switched careers or jobs switched banks during that life event.
Life events create windows of opportunity—but they differ by generation.
A career change looks like an unusually strong acquisition moment among Millennials at 37%. Home purchases, marriage, parenthood and retirement open different windows, and they open for different people: the events that move a Gen Z consumer are not the events that move a Boomer, and for several combinations the report publishes no figure at all.
The implication for banks and credit unions is not simply to market around life events. It is to know which events matter among the consumers you are trying to acquire, what financial need appears at that moment and which institutions those consumers are already considering when it does.
The second account
Consumers may also add a new bank without leaving their primary institution.
Rivel found meaningful account-opening activity outside the consumer's primary institution during several life events:
| Life event | Gen Z | Millennials | Gen X | Boomers |
|---|---|---|---|---|
| Joined the workforce | — | 13% | — | — |
| Got married | — | 10% | — | — |
| Became a parent | 20% | 19% | — | — |
| Switched careers or jobs | — | 14% | 13% | — |
| Bought a home | 15% | 25% | 18% | — |
This distinction matters: a life event can create an acquisition opportunity even when the consumer does not immediately transfer the full primary banking relationship.
How smaller institutions win consideration without winning the whole relationship
Research in practice
A blueprint for outsmarting competitors
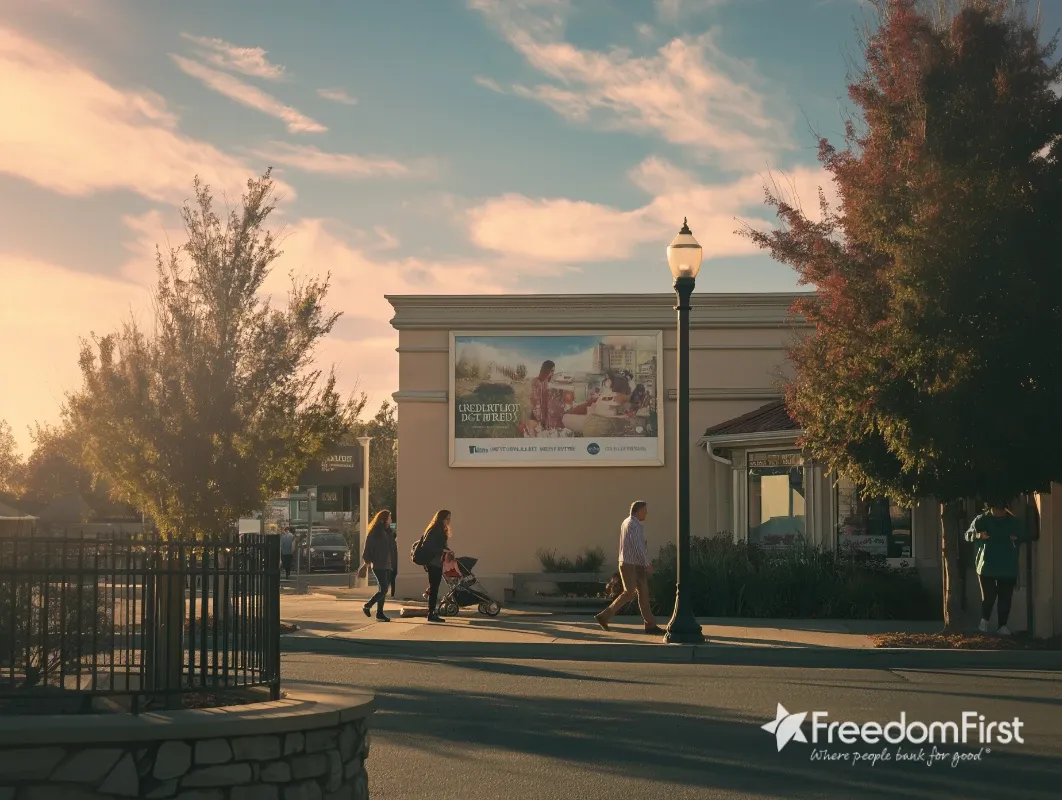
Armed with footprint-specific insights, Freedom First Credit Union turned local consumer and business pain points into bold billboard messaging.
What they did
By spotlighting frustrations with key competitors, Freedom First built campaign messaging around what people in their own footprint were actually dissatisfied with, rather than around a national picture.
What followed
They grew brand awareness and established themselves as an attractive banking option in the region.
Who they listen to
What influences consumers when they select a new bank or product?
Across five key life events, family or friend recommendations were among the strongest influences. Consumers also cited digital marketing, their primary financial institution, their own research, specific bank promotions and physical marketing.
| Channel | Joined workforce | Got married | Became a parent | Switched careers | Bought a home |
|---|---|---|---|---|---|
| Family/friend recommendation | 29% | 23% | 30% | 30% | 34% |
| Digital marketing | 26% | 22% | 20% | 23% | 30% |
| Used primary FI | 24% | 34% | 26% | 25% | 29% |
| Did my own research | 22% | 22% | 27% | 26% | 34% |
| Specific bank promotion | 22% | 15% | 23% | 26% | 22% |
| Physical marketing | 16% | 15% | 17% | 20% | 29% |
Reputation gets you considered. Relevance helps you win the moment.
Timing and relevance should complement—not replace—brand reputation. A life event can make a consumer more receptive to changing or expanding a financial relationship, but an institution still needs enough awareness and credibility to be a realistic choice when that moment arrives.
Four disciplines
What should banks and credit unions do with this research?
Target the event, not the age band
The events that move a consumer are not the same across generations. A career change is the strongest switching moment among Millennials at 37%—for Gen X it is a home purchase. Aim at the event your audience is actually having.
Match the channel to the moment
Family and friends carry the most weight with home buyers at 34%, but the newly married are most influenced by the institution they already bank with. One acquisition channel does not serve every life event.
Compete for the second account, not just the switch
A quarter of Millennials who bought a home opened an account elsewhere without moving their primary bank. Winning part of a relationship is a different offer from winning all of it.
Benchmark against the institutions consumers actually consider
National averages give context. Growth decisions need to know how your institution performs against that set, market by market.
From national pattern to local decision
Your market has its own version of these numbers.
Rivel Banking Research benchmarks consumer perception, consideration and competitive position for banks and credit unions across the United States, from 220,000 consumer and small-business interviews a year, with benchmarks refreshed every six months.
The national findings on this page identify the pattern. Institution- and market-level research is what shows how that pattern lands in one footprint:
- Your competitive set. How consumers perceive your institution against the banks and credit unions they actually consider—not against a national average.
- Your growth opportunities. The audiences, markets and perceptions where there is room to gain consideration or deepen a relationship.
- Interpretation, not just data. What moved, why it matters and what to do about it, rather than a file of results.
Methodology
About the research
- Study
- Banking on Life: How Life Events and Generational Differences Shape Financial Decisions
- Research organisation
- Rivel Banking Research
- Field period
- April 2025
- Geography
- United States
Published: . Last reviewed: .
About these figures: The percentages here are reproduced as published in Banking on Life. The report does not publish sample sizes or margins of error for the individual generational figures, so none are shown.
Stay current
Keep up with the latest banking research findings.
Published twice a year. We’ll email you each time.
FAQs
Frequently asked questions about bank switching
How many consumers are vulnerable to switching banks?
Rivel's research, refreshed every six months, indicates about 33% of consumers are vulnerable to switching their primary banking relationship at any given time.
Which generation is most vulnerable to switching?
In the April 2025 research cited in Banking on Life, Millennials had the highest overall vulnerability metric at 37%.
Do life events cause consumers to switch banks?
Rivel's research shows that switching and new account activity occur during major life events, but the published report describes associations and opportunities rather than proving that a life event alone causes a switch.
What is the most influential channel when consumers choose a new bank?
Across the life events shown in Rivel's report, family or friend recommendations were among the strongest influences, reaching 34% for consumers buying a home. Other important influences included consumers' own research, digital marketing and their existing financial institution.
See the full banking research FAQ—scope, methodology, reporting and focus groups →
Get started
Understand switching risk in your market.
Rivel Banking Research can benchmark consumer perceptions, competitor strengths and market opportunities for your institution's footprint.